
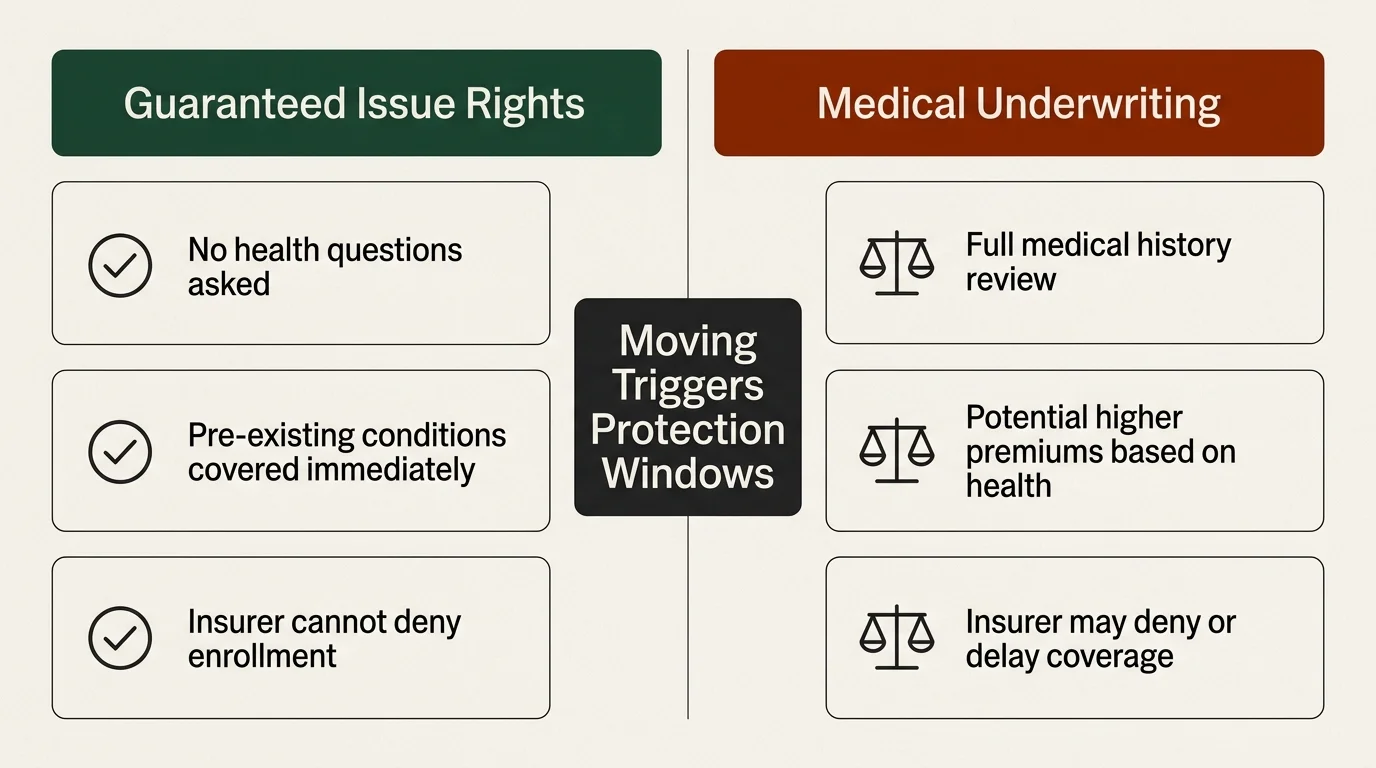
Guaranteed Issue Rights vs. Medical Underwriting
If you decide to switch Medigap policies after moving—perhaps to find a lower premium or a carrier with stronger local customer support—you enter a different legal landscape. Outside your initial six-month Medigap Open Enrollment Period (which begins when you are 65 or older and enrolled in Part B), private insurance carriers in most states can subject you to medical underwriting.
Under medical underwriting, insurance companies evaluate your complete health history, medical diagnoses, and prescription usage. They maintain full authority to charge higher premiums or deny your application entirely based on pre-existing conditions. Moving to a new state does not automatically grant you a federal “guaranteed issue right” to purchase a new Medigap plan from a different carrier, unless your move forces you out of a specific type of plan called Medicare SELECT.
Medicare SELECT is a localized type of Medigap policy that requires you to use specific regional hospital networks for non-emergency care. If you move out of your Medicare SELECT policy’s network area, federal law grants you a guaranteed issue right to purchase a standard Medigap policy (such as Plan A, B, C, F, K, or L) from any carrier in your new state without undergoing medical underwriting.

Leave a Reply