
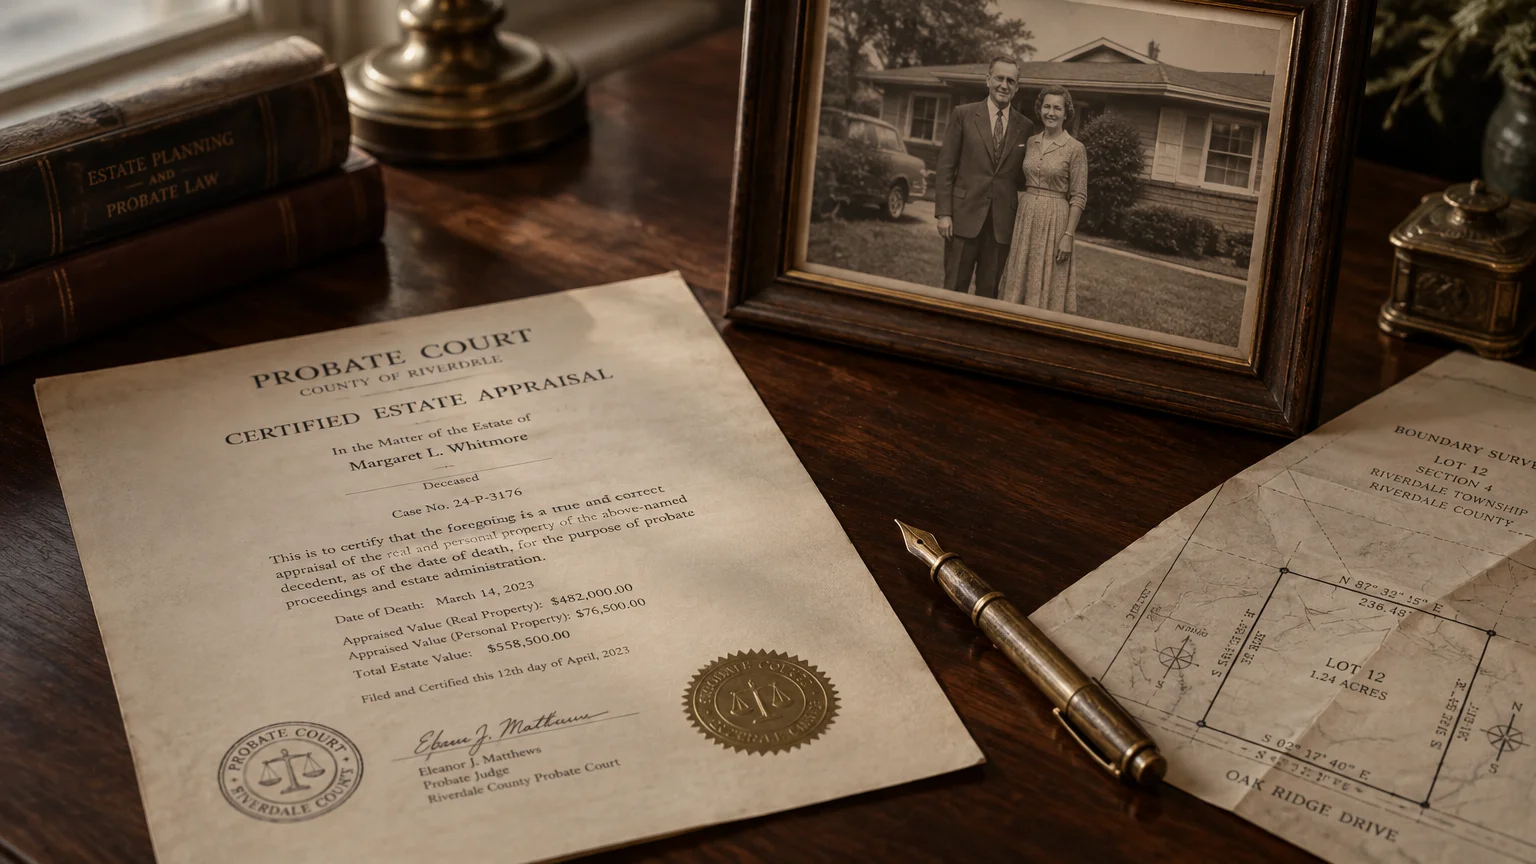
Inherited Homes and Stepped-Up Basis Records
Inheriting a residence brings substantial tax advantages through the stepped-up basis provision under IRC Section 1014. The property’s cost basis resets to fair market value on the decedent’s date of death.
The stepped-up basis wipes away decades of accrued capital gains accumulated by the previous owner. However, heirs must document this new starting valuation accurately.
Obtain a professional real estate appraisal from a licensed appraiser immediately following the decedent’s passing. Estate tax filings on Form 706 also serve as acceptable valuation proof.
Retain that date-of-death appraisal report for as long as you hold the inherited property, plus three to six years after you file the sale return.
“An investment in knowledge pays the best interest.” — Benjamin Franklin, Founding Father & Polymath
Understanding basis step-up rules protects family estates from thousands of dollars in unnecessary capital gains liabilities. Accurate documentation preserves generational wealth during inheritance transitions.
To many pop ups this website is tooooo difficult to read!
How long do you have to keep tax returns and accompanying documents if you DON’T own a home?