10. Practical Financial Strategies to Bridge the End-of-Life Gap
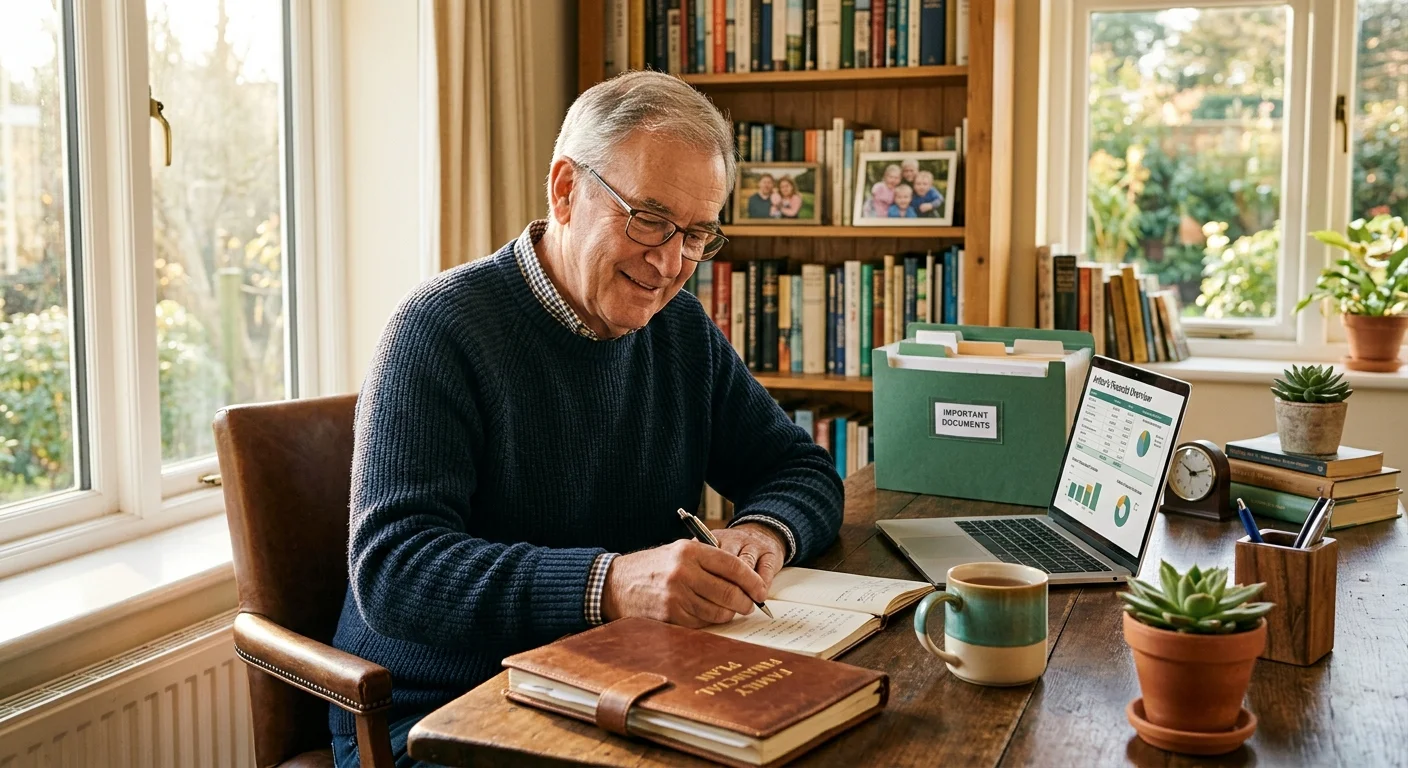
Because the $255 payment covers only a fraction of actual final expenses, proactive planning is essential. Implementing reliable financial tools protects surviving relatives from emergency borrowing or high-interest credit card debt.
Consider four effective financial strategies to cover final costs:
- Payable-on-Death (POD) Accounts: You can add a Payable-on-Death designation to standard checking or savings accounts. This allows designated beneficiaries to access liquid cash immediately upon presenting a death certificate, bypassing probate court delays.
- Final Expense Life Insurance: Small, targeted whole life insurance policies—often called funeral insurance or burial policies—provide immediate payouts ranging from $5,000 to $25,000 to cover immediate expenses.
- Pre-Need Funeral Contracts: Working directly with a licensed funeral facility allows you to select services and lock in current prices, shielding your family from future inflation.
- Dedicated Savings Accounts: Maintaining a liquid emergency fund earmarked specifically for end-of-life administrative costs gives your family immediate financial flexibility.
“Do not leave your loved ones with a financial puzzle during an emotional crisis; structure your liquid assets so cash is available immediately when needed.” — Suze Orman, Personal Finance Expert
Review general senior wellness and economic security planning tools through the National Council on Aging to build a comprehensive financial foundation.
$255 death benefit