Retired in America

Your Guide to a Confident Retirement

  • Home
  • Personal finance
  • Retirement Life
  • Saving & Spending

2027 IRMAA Bracket Forecast: Estimated Income Thresholds by Filing Status

August 4, 2026 · Personal finance

What Can Go Wrong

A frustrated woman sits by spilled batter, illustrating how easily plans can go wrong.

What Can Go Wrong

Retirees often slip into higher Medicare brackets unintentionally due to common oversight errors. Avoid these frequent pitfalls when managing your income strategy:

  • Assuming Municipal Bond Interest Is Excluded: Many investors believe tax-exempt interest from state and local bonds avoids Medicare scrutiny. In reality, municipal interest is added directly back into AGI when calculating IRMAA MAGI.
  • Failing to Coordinate Large One-Time Inflows: Selling a primary home, cashing out an annuity, or taking a large lump-sum pension distribution in 2025 will drastically bump your MAGI. Without planning, these moves cause an unexpected surge in 2027 healthcare expenses.
  • Ignoring Spousal Double-Impact: For married couples enrolled in Part B and Part D, IRMAA surcharges hit both individuals. Crossing a threshold by $1 doubles the penalty at the household level.
  • Delaying Appeals: If you experience a qualifying life event in 2026 or 2027, waiting to file Form SSA-44 means Medicare will automatically deduct higher premiums from your Social Security checks until the error is corrected.
When to Consult a Professional
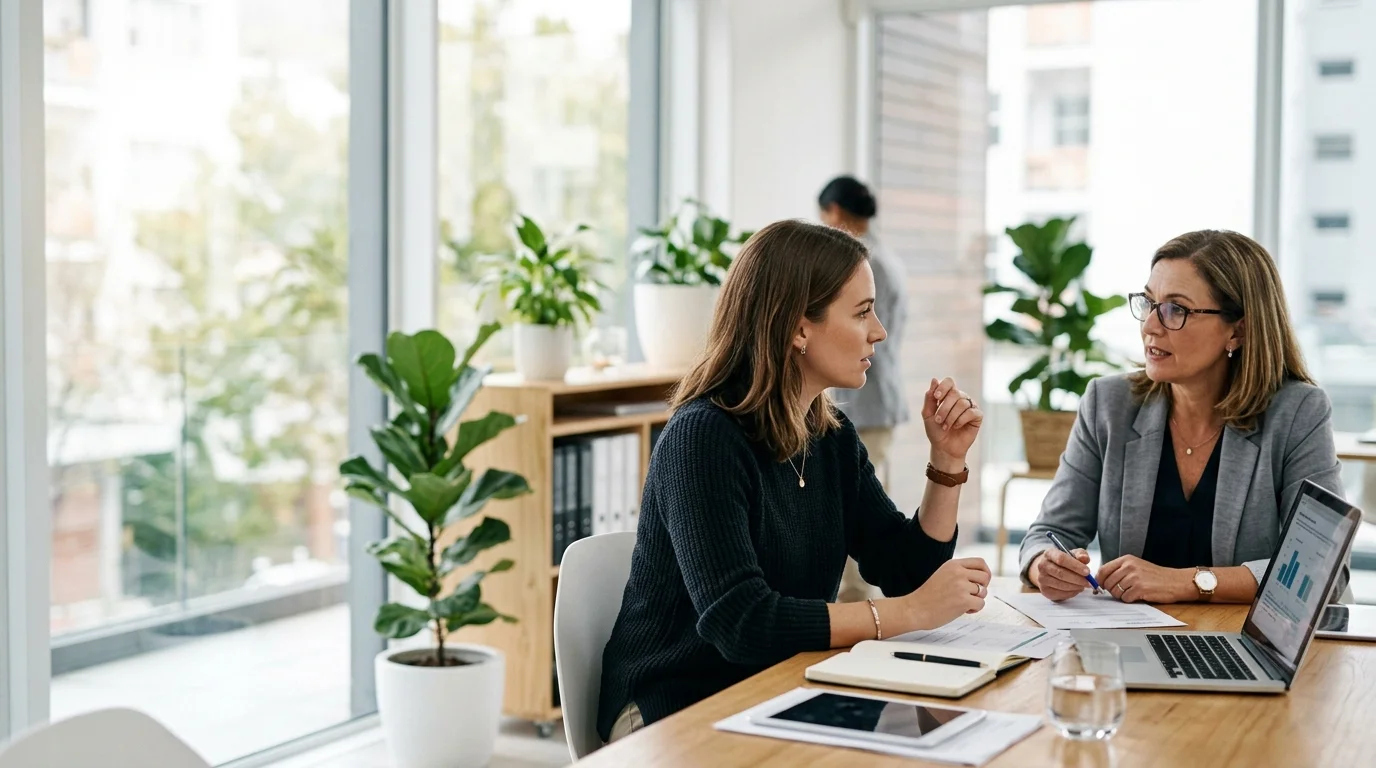
A financial advisor guides a client through complex planning data on a laptop in a bright office.

When to Consult a Professional

While basic income tracking is straightforward, managing complex retirement tax levers often requires expert assistance. Consider working with a Certified Financial Planner (CFP) or Certified Public Accountant (CPA) in the following scenarios:

  • Planning Major Roth Conversions: An advisor can help you execute multi-year Roth conversions that optimize your long-term tax rates without triggering unexpected Medicare brackets.
  • Selling Real Estate or Business Assets: Professional tax modeling can structure sales through 1031 exchanges, installment sales, or loss-harvesting strategies to keep your 2025 MAGI manageable.
  • Navigating the Death of a Spouse: Losing a spouse brings emotional hardship alongside the “single penalty”—where filing thresholds drop significantly while income from pensions or investments may remain high.
  • Structuring RMD Strategies: If impending RMDs threaten to push you into permanent high-tier surcharges after age 73, a financial planner can establish coordinated withdrawal plans using QCDs or split-annuity options.

Frequently Asked Questions

When will Medicare release the official 2027 IRMAA numbers?

The Centers for Medicare & Medicaid Services (CMS) typically publishes the official Medicare Part B baseline premiums and final IRMAA brackets in November 2026. However, your 2027 surcharge relies on your 2025 tax return, making advance planning necessary long before official figures are released.

Does Medicare Part D have its own IRMAA surcharge?

Yes. If your MAGI triggers an IRMAA surcharge for Part B, you must also pay a monthly IRMAA surcharge for Medicare Part D prescription coverage. This fee is paid directly to Medicare or deducted from your Social Security benefit, in addition to your standard plan premium.

Can a one-time income surge affect my Medicare premiums forever?

No. IRMAA calculations are updated annually using a rolling two-year lookback period. A high 2025 income increases your premiums only during calendar year 2027. If your income returns to normal levels in 2026, your 2028 premiums drop back down accordingly.

What if my income drops in 2026 or 2027 after I retire?

If your income drops because of a qualifying life-changing event—such as work stoppage or work reduction—you do not have to wait two years for your premiums to adjust. File Form SSA-44 with the Social Security Administration to request an immediate surcharge reduction based on your lower estimated current income.

Next Steps for Your Retirement Plan

Managing Medicare costs requires active preparation well before you receive your annual benefit notices. Review your anticipated 2025 earnings, taxable investment returns, and distribution schedules right away. Small adjustments made before year-end can keep your income under critical threshold limits and protect your retirement income from unexpected surcharges.

Take time to audit your portfolio, consult your financial advisor, and evaluate whether strategies like Qualified Charitable Distributions or tax-loss harvesting make sense for your situation. Protecting your nest egg is an ongoing process, and controlling your healthcare overhead is one of the most effective ways to preserve your financial independence.

This article provides general retirement education and information only. Every retiree’s situation is unique—what works for others may not work for you. For personalized advice, consider consulting a qualified financial professional such as a CFP or CPA.


Last updated: March 2026. Retirement benefits, tax rules, and healthcare regulations change frequently—verify current details with official sources.
Pages: 1 2 3 4 5 6 7

Share this article

Facebook Twitter Pinterest LinkedIn Email

Leave a Reply Cancel reply

Your email address will not be published. Required fields are marked *

Search

Latest Posts

  • A senior man sitting at a wooden table examines an investment portfolio document next to a notebook and coffee mug. 4 Boring Moves To Do Now to Add Hundreds to Your Social Security Check
  • A senior woman sits at a wooden table holding a mug and gazing out a bay window beside a newspaper and open notebook. 9 Things Single or Widowed Retirees Should Know
  • Senior couple sitting at a wooden kitchen table reviewing paperwork and financial notes with a calculator and coffee. 10 Financial Traps That Catch Retirees Off Guard
  • A smiling senior woman reaches into a wooden pull-out drawer filled with labeled food jars in a sunlit kitchen. 15 Simple Fixes for Everyday Senior Life
  • Older man in a green jacket reading a pamphlet beside a wooden arrow sign pointing toward voter information. The Issues Voters Say Matter Most Heading Into November
  • A settlement statement paper on a desk alongside file boxes labeled closing documents, property taxes, and renovations. Here's How Long You Should Keep Tax Records If You Own a Home
  • A senior woman sits at a wooden dining table reviewing a monthly checking statement alongside a notebook and coffee mug. 5 States With Extra Payments on Top of Federal Benefits
  • Older couple walking down a sunny small-town sidewalk past brick storefronts, a hardware store, and a bakery. The 10 Best Small Towns for Retirees to Stretch a Social Security Check
  • An older man in a denim jacket organizes hardware behind a store counter beside a shift schedule notebook. What Happens to Your Social Security If You Work Part-Time After 65
  • A stressed older couple sits on the floor of an empty living room surrounded by unpacked cardboard moving boxes. 5 States Retirees Regret Moving to, Based on Cost and Lifestyle

Newsletter

Get retirement planning tips, savings strategies, and lifestyle insights delivered to your inbox.

Related Articles

An older man at a wooden kitchen table reviews a long pharmacy receipt next to a prescription bottle in warm morning light.

8 Signs Your Medicare Plan’s Drug Formulary Has Changed

Discover the 8 critical signs your Medicare drug formulary has changed, how to spot unexpected…

Read More →
10 Things Teachers Should Know About Their Pension Before Retiring

10 Things Teachers Should Know About Their Pension Before Retiring

Learn the 10 essential teacher pension facts before retiring, including payout options, survivor benefits, tax…

Read More →
A senior woman looking thoughtfully at her phone in a bright, modern home office.

6 Social Security Scams You Need to Pay Attention to

Protect your retirement income by learning how to spot, avoid, and report the six most…

Read More →

10 Quick Ways to Earn Some Extra Cash During Retirement

6. Doing landscaping or gardening If people admire your beautiful garden and wish they’d have…

Read More →
An older man sits at a kitchen table looking cautiously at his smartphone next to a Social Security statement and a warm mug.

How to Spot Social Security Phone and Email Scams Targeting Retirees

Learn how to identify and stop Social Security phone and email scams before they drain…

Read More →
Senior couple sitting at a wooden kitchen table reviewing Medicare summary notices and financial documents.

Medicare Changes in 2027: What You’ll Actually Pay

Learn what you will actually pay under 2027 Medicare changes, including Part B premiums, IRMAA…

Read More →

9 401(k) Mistakes & Solutions All Boomers Should Be Aware Of

6th Mistake: Not Creating a Budget for Before and After Retirement Baby boomers believe that…

Read More →

How 8 Types of Retirement Income Get Taxed

Annuities For many seniors, annuities are a great way to add up to your retirement…

Read More →

12 Creative Ways To Earn Passive Income in Retirement

Rent your outdoor adventure vehicles – If you’re the proud owner of an RV, camper van,…

Read More →
Retired in America

Your Guide to a Confident Retirement

Inedit Agency S.R.L.
Bucharest, Romania

contact@retiredinamerica.com

Trust & Legal

About Us

Editorial Policy

Advertiser Disclosure

Frequently Asked Questions

Contact Us

Disclaimer

Terms and Conditions

Privacy Policy

Subscribe

Unsubscribe

Categories

  • Personal finance
  • Retirement Life
  • Saving & Spending

© 2026 Retired in America. All rights reserved.