Comparing 2026 and 2027 Social Security Rules
Reviewing key thresholds side-by-side helps you grasp the broader scope of social security 2027 changes. Multiple inflation-adjusted metrics shift simultaneously each January.
| Program Provision | 2026 Limit | 2027 Limit | Impact on Working Beneficiaries |
|---|---|---|---|
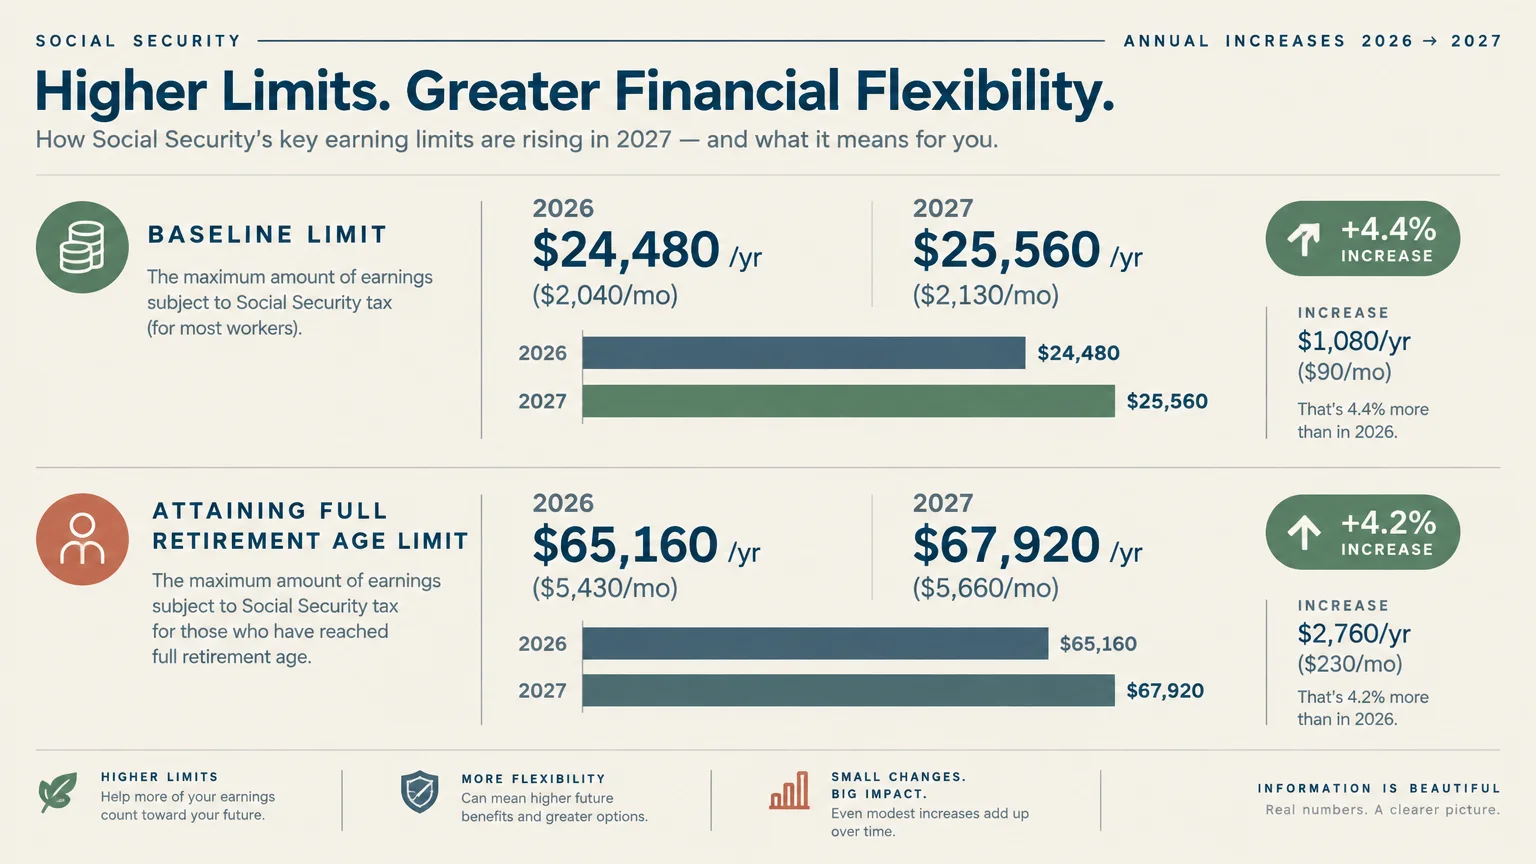
| Earnings Limit (Under FRA All Year) | $24,480 / year ($2,040 / month) | $25,560 / year ($2,130 / month) | Allows an extra $1,080 in annual earnings before benefit withholdings begin. |
| Withholding Rate (Under FRA) | $1 withheld per $2 over limit | $1 withheld per $2 over limit | Rate remains unchanged for early claimants. |
| Earnings Limit (Year Reaching FRA) | $65,160 / year ($5,430 / month) | $67,920 / year ($5,660 / month) | Allows an extra $2,760 in earnings prior to your birth month. |
| Withholding Rate (Year of FRA) | $1 withheld per $3 over limit | $1 withheld per $3 over limit | Only applies to earnings prior to the month you reach age 67. |
| Cost-of-Living Adjustment (COLA) | 2.8% | 3.6% | Increases monthly benefit checks across the board starting in January 2027. |
| Average Monthly Retired Worker Check | $2,095 | $2,170 | Represents an average boost of $75 per month for retired workers. |
| Maximum Taxable Wage Cap | $184,500 | $192,300 | Higher earners pay the 6.2% payroll tax on an additional $7,800 of wage income. |
| Earnings Required per Work Credit | $1,890 | $1,970 | Workers need $7,880 in annual earnings to earn the maximum four coverage credits. |
| Maximum Benefit at Full Retirement Age | $4,152 / month | $4,188 / month | Applies to workers retiring at full retirement age with top career earnings. |
These adjustments reflect broader economic data evaluated by federal actuaries. They balance inflation pressures against the financial obligations of the trust funds.
The Myth of Lost Benefits: How Withholding Actually Works
One of the most persistent misconceptions among working retirees social security recipients is that withheld benefits vanish forever. That belief is incorrect.
When the government holds back benefits due to the earnings test 2027 rules, it simply delays payment. The money is not a fine, a penalty, or an added tax.
Once you reach your full retirement age, the agency recalculates your benefit amount automatically. They adjust your monthly payment upward to credit you for every month a check was withheld.
For instance, suppose you claimed benefits at age 62, accepting an initial permanent reduction of 30 percent. If your wages cause the agency to withhold 12 full checks before you reach 67, your reduction factor changes.
At age 67, the agency recalculates your check as if you claimed four years early instead of five. Your ongoing monthly benefit increases permanently to make up for the earlier withholdings.
Over an average lifespan, you often recoup the full value of the withheld funds. Knowing this removes much of the anxiety surrounding working while collecting benefits.