The Internal Revenue Service has officially released the federal income tax brackets for 2027, giving retirees wider tax bands and higher standard deductions. These adjustments help shield your fixed income and retirement distributions from persistent inflationary pressures.
Thanks to an average 3.2% inflation adjustment, you can earn more money before bumping into higher marginal tax rates. This upward shift provides an immediate opportunity to optimize your withdrawal schedules and Roth conversion plans.
Understanding these updated numbers ensures you keep more of your hard-earned wealth throughout your retirement years. Here is what the official 2027 changes mean for your household budget and tax planning strategy.
Understanding the 2027 Federal Income Tax Brackets
On November 5, 2026, the IRS issued Revenue Procedure 2026-35, setting the official tax rate schedules for tax year 2027. You will use these brackets when filing your federal tax return in early 2028.
The adjustments reflect an inflation increase of roughly 3.2% across all income tiers. This chained Consumer Price Index calculation prevents bracket creep, which occurs when cost-of-living adjustments push you into higher brackets without real purchasing gains.
Federal tax policy maintains seven marginal income tax brackets for 2027: 10%, 12%, 22%, 24%, 32%, 35%, and 37%. These marginal percentages remain permanently locked following comprehensive tax legislation enacted in 2025.
Under the Working Families Tax Cuts, Congress permanently extended the marginal rate structures originally established under the 2017 tax reforms. Consequently, retirees no longer face the looming threat of the automatic tax increases once scheduled for 2026 and beyond.
Each marginal bracket applies only to income that falls within that specific band. Earning an extra dollar that nudges you into a higher bracket never subjects your entire income to that elevated rate.
For single filers, the lowest 10% rate covers taxable income up to $12,800. Married couples filing jointly can earn up to $25,600 before entering the 12% bracket.
The popular 12% bracket now extends up to $52,025 for singles and $104,050 for joint filers. Many retirees intentionally fill this bracket with traditional IRA distributions while tax rates remain historically low.
Moderate earners will pay 22% on taxable income up to $109,125 for singles and $218,250 for married couples. The 24% bracket reaches up to $208,325 for individuals and $416,650 for joint filers.
Higher earners encounter the 32% bracket starting above $208,325 for single taxpayers and $416,650 for married couples. The 35% tier begins at $264,550 for singles and $529,100 for married partners.
The top 37% rate begins at $661,375 for single individuals and $793,650 for married couples filing joint returns. You can review the full procedural release directly on the Internal Revenue Service (IRS) website.
| Marginal Tax Rate | Single Filers | Married Filing Jointly |
|---|---|---|
| 10% | Up to $12,800 | Up to $25,600 |
| 12% | $12,801 to $52,025 | $25,601 to $104,050 |
| 22% | $52,026 to $109,125 | $104,051 to $218,250 |
| 24% | $109,126 to $208,325 | $218,251 to $416,650 |
| 32% | $208,326 to $264,550 | $416,651 to $529,100 |
| 35% | $264,551 to $661,375 | $529,101 to $793,650 |
| 37% | Over $661,375 | Over $793,650 |
To see how these rates apply, imagine you are a single retiree with $60,000 of taxable income in 2027. Your first $12,800 faces a 10% tax, the portion up to $52,025 incurs 12%, and only the remaining $7,975 pays 22%.
This progressive structure produces an effective tax rate that remains substantially lower than your top marginal bracket. Knowing your exact bracket ceilings lets you withdraw funds from tax-deferred accounts without triggering unexpected tax spikes.
Standard Deductions and Major Senior Deductions for 2027
Most American retirees claim the standard deduction rather than itemizing deductions on Schedule A. For the 2027 tax year, the base standard deduction rises to match ongoing inflation.
Single filers and married individuals filing separately receive a base standard deduction of $16,600, representing a $500 increase over 2026. Married couples filing jointly receive an extra $1,000, bringing their base deduction to $33,200.
Heads of household claim a standard deduction of $24,925, an increase of $775 from the previous year. These higher deductions exempt a larger baseline of income before federal income tax calculations begin.
Older Americans also receive an additional age-based standard deduction once they reach age 65. You qualify for this extra deduction starting in the tax year you turn 65.
For 2027, the additional standard deduction for age 65 or older reaches $2,100 for unmarried filers. For married couples, each qualifying spouse age 65 or older receives an extra $1,700 deduction.
A single retiree age 65 or older receives a combined deduction of $18,700. A married couple with both spouses age 65 or older receives a combined standard deduction of $36,600.
Retirees also benefit from the temporary $6,000 senior deduction enacted in 2025. This specialized tax relief remains active for tax years 2025 through 2028.
Eligible individuals age 65 and older can claim an additional $6,000 deduction per person. If you and your spouse are both 65 or older, you claim an additional $12,000 deduction on your joint return.
This special senior deduction stacks directly on top of both your base standard deduction and your age-based deduction. Seniors who choose to itemize deductions can also claim this $6,000 allowance.
By stacking all three deductions, a single senior age 65 or older can shelter up to $24,700 in tax-free income in 2027. A married couple where both spouses are 65 or older can shield an impressive $48,600 before owing any federal income tax.
Be aware that this temporary $6,000 senior deduction features an income phase-out rule. The deduction phases out at a rate of 6% for Modified Adjusted Gross Income exceeding $75,000 for single filers and $150,000 for joint filers.
| Deduction Component | Single Senior (Age 65+) | Married Seniors (Both 65+) |
|---|---|---|
| Base Standard Deduction | $16,600 | $33,200 |
| Age 65+ Additional Deduction | $2,100 | $3,400 ($1,700 each) |
| Temporary Senior Deduction | $6,000 | $12,000 ($6,000 each) |
| Total Tax-Free Income | $24,700 | $48,600 |
This triple-stacked deduction structure provides unprecedented shelter for pension distributions and IRA withdrawals. Planning your income carefully keeps you below the phase-out limit while maximizing this temporary tax advantage.
Long-Term Capital Gains and Qualified Dividends in 2027
Taxable brokerage accounts offer distinct financial advantages because long-term capital gains and qualified dividends receive preferential tax treatment. Assets held longer than one year qualify for federal tax rates of 0%, 15%, or 20%.
The IRS adjusted the capital gains tax brackets upward by approximately 3.2% for 2027. These expanded thresholds give investors greater flexibility when rebalancing portfolios or selling appreciated assets.
Single filers enjoy a 0% capital gains rate on taxable income up to $51,050 in 2027. Married couples filing jointly pay 0% on long-term gains and qualified dividends up to $102,100.
Heads of household pay 0% on capital gains up to $68,350. This zero-percent bracket creates powerful opportunities for retirees living primarily on savings or municipal bonds.
The 15% capital gains bracket covers taxable income up to $563,200 for single filers and $633,600 for married joint filers. Heads of household pay 15% on taxable income up to $598,400.
Taxable income surpassing $563,200 for singles and $633,600 for joint filers faces the top 20% capital gains rate. High-income investors must also plan for the separate 3.8% Net Investment Income Tax above statutory MAGI thresholds.
Your ordinary income fills your lower tax brackets first before the IRS counts your capital gains. If your ordinary income already fills the 0% bracket, your capital gains will fall into the 15% tier.
You can harvest capital gains tax-free in years when your ordinary income remains exceptionally low. Selling appreciated index funds while within the 0% bracket resets your investment cost basis without creating a tax liability.
To learn more about tracking investment cost basis and dividend classifications, consult comprehensive educational guides on Investopedia. Tracking holding periods accurately prevents costly short-term capital gains penalties.
Social Security, COLA Adjustments, and the Tax Torpedo
Social Security benefits will increase by 3.6% in 2027 under the annual Cost-of-Living Adjustment. While higher checks help pay everyday living expenses, they also push more seniors into taxable territory.
For working retirees, the Social Security taxable wage cap increases to $192,300 in 2027. Earnings up to that amount face the standard 6.2% Social Security payroll tax deduction.
Unlike federal tax brackets, the income thresholds determining Social Security benefit taxation are never adjusted for inflation. Congress established these statutory triggers in 1983 and 1993, leaving them permanently frozen.
Up to 50% of your Social Security benefits become taxable when your combined income exceeds $25,000 for single filers or $32,000 for married couples. Up to 85% becomes taxable if your combined income exceeds $34,000 for singles or $44,000 for joint filers.
The IRS defines combined income as your Adjusted Gross Income plus non-taxable interest, plus exactly half of your gross Social Security benefits. Because of frozen thresholds, your 3.6% COLA raise can inadvertently drag more of your benefits onto your tax return.
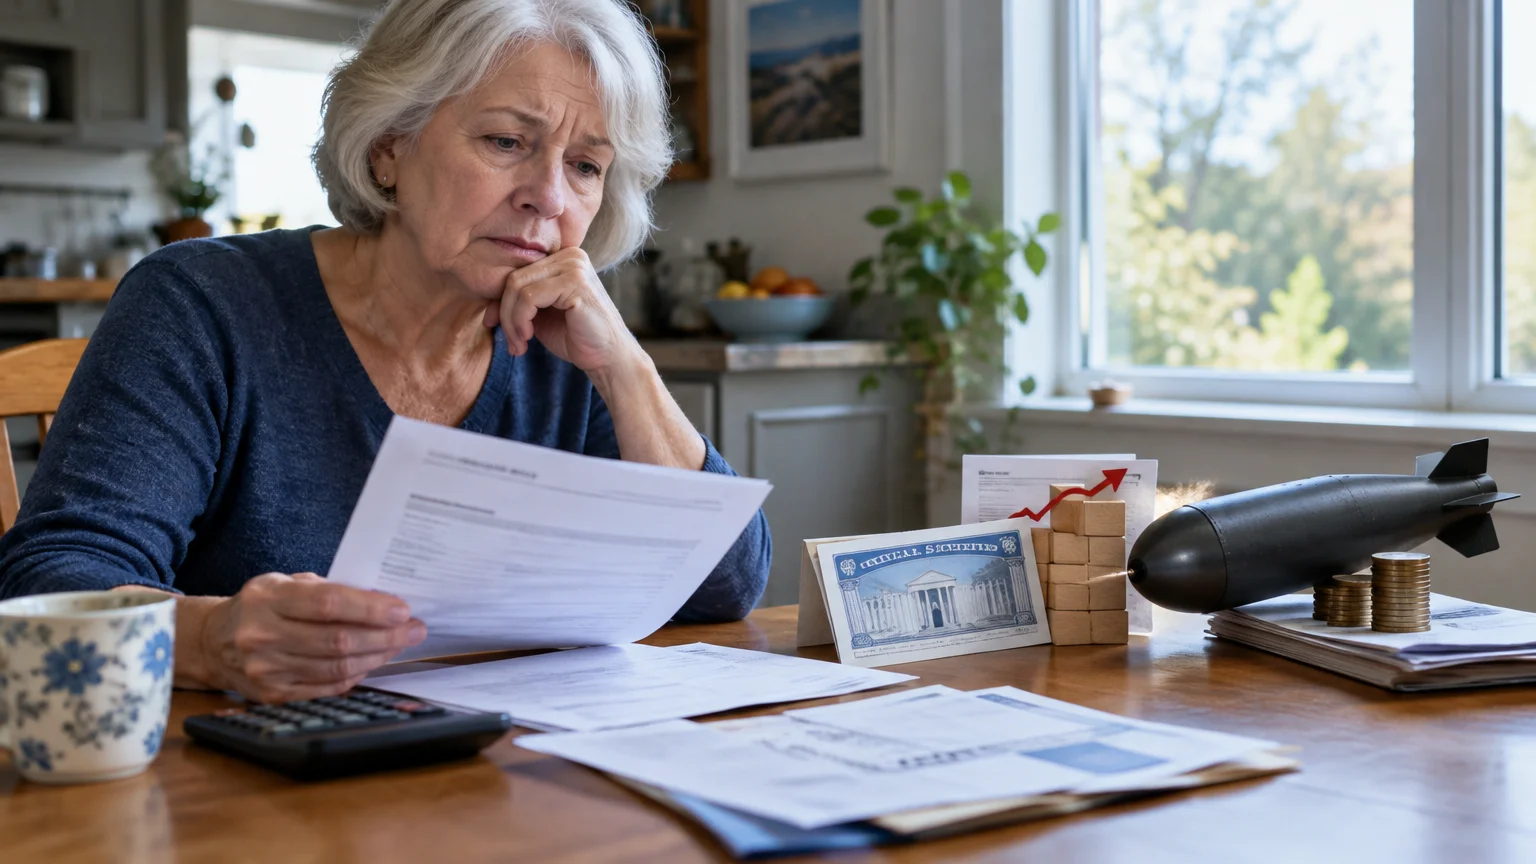
Financial planners refer to this sudden compounding tax effect as the retirement tax torpedo. As each dollar of IRA income makes an additional 85 cents of Social Security taxable, your marginal rate can surge unexpectedly.
You can review your personalized benefit statements and earnings history through the official Social Security Administration (SSA) portal. Monitoring your combined income helps you time distributions from Roth accounts to avoid triggering the 85% benefit tax tier.
“Tax planning is not a once-a-year event; it is an everyday financial habit that protects your future.” — Suze Orman, Personal Finance Author
Balancing withdrawals across multiple account types keeps your taxable income beneath critical thresholds. Strategic planning ensures your annual COLA increase supports your retirement rather than expanding your tax bill.
Retirement Planning Opportunities and the New 2027 Saver’s Match
The 2027 tax brackets open concrete planning opportunities for proactive retirees. Adjusting your financial schedule around these official thresholds will generate substantial tax savings.
First, evaluate partial Roth conversions up to the top of the 12% or 22% bracket limits. A married couple can realize up to $104,050 of taxable income in 2027 while paying a modest 12% marginal rate.
Converting pre-tax balances into a Roth IRA locks in low current rates and eliminates future Required Minimum Distributions. Converted funds grow tax-free and provide tax-exempt income later in retirement.
Second, retirees age 70½ or older should leverage Qualified Charitable Distributions directly from their traditional IRAs. You can transfer funds directly to qualified charities without counting that money as taxable income.
Because QCDs bypass your Adjusted Gross Income, they preserve your eligibility for the temporary $6,000 senior deduction. They also prevent spikes in your combined income that could tax your Social Security benefits.
Third, lower-to-middle-income retirees who maintain part-time earned income should evaluate the new federal Saver’s Match launching in 2027. Enacted under SECURE 2.0, this program completely replaces the old non-refundable Saver’s Credit.
The federal government provides a direct 50% matching contribution, up to $1,000 per person, deposited into your designated retirement account. This match acts as free money added directly to your nest egg.
The full 50% match applies to Modified Adjusted Gross Income up to $20,500 for single filers and $41,000 for joint filers. The match phases out entirely once MAGI reaches $35,500 for single taxpayers and $71,000 for married couples.
Regarding employer plan savings, the IRS has not yet officially released the 2027 retirement plan contribution limits as of November 2026. Actuarial projections estimate that employee 401(k) limits will rise toward $25,500, but verify final IRS notices before adjusting salary deferrals.
- Fill your 10% and 12% brackets with strategic Roth conversions before rates change.
- Use Qualified Charitable Distributions to satisfy charitable giving without increasing your AGI.
- Claim the new federal Saver’s Match if you earn modest wage income in retirement.
- Verify official IRS notices later this year before locking in 2027 retirement account contributions.
Disciplined execution across these areas ensures you take full advantage of every federal incentive available. Combining these strategies delivers a resilient, tax-efficient distribution structure.
Estate and Gift Tax Updates You Should Know
High-net-worth retirees can take advantage of expanded wealth transfer limits in 2027. The federal basic estate and gift tax exclusion rises to $15.48 million per individual.
A married couple using portability elections can protect up to $30.96 million from federal estate and generation-skipping taxes. This historic exclusion shields nearly all families from federal estate tax exposure.
The annual gift tax exclusion increases to $20,000 per recipient for tax year 2027. A married couple can give up to $40,000 per child or grandchild each year without filing IRS Form 709.
Annual gifting moves assets out of your taxable estate while providing immediate financial assistance to children or grandchildren. These gifts do not reduce your lifetime $15.48 million exclusion limit.
Making direct payments to educational institutions for tuition or to medical facilities for healthcare costs avoids gift taxes entirely. These direct transfers do not count toward your annual $20,000 gift exclusion limit.
Reviewing beneficiary designations on retirement accounts remains equally vital for estate protection. Inherited traditional IRAs generally require non-spouse heirs to withdraw all funds within ten years under current federal statutes.
What Can Go Wrong: Pitfalls Retirees Must Avoid
Retirement tax planning involves interconnected rules where a single misstep can create cascading financial penalties. Staying informed prevents costly errors when managing your finances.
The most common error is ignoring the phase-out range for the temporary $6,000 senior tax deduction. Every dollar of MAGI earned above $75,000 for singles or $150,000 for couples reduces this valuable deduction by six cents.
Another dangerous trap involves triggering Medicare Income-Related Monthly Adjustment Amount surcharges, known as IRMAA. IRMAA surcharges are calculated using your tax return from two years prior.
Crossing an IRMAA threshold by a single dollar increases your Medicare Part B and Part D premiums for the entire calendar year. Check current premium thresholds on Medicare.gov before realizing substantial capital gains or completing large Roth conversions.
Taking unscheduled lump-sum withdrawals from traditional IRAs to fund home renovations or vehicle purchases can also backfire. A large distribution can push your income into a higher bracket, eliminate your senior deduction, and make 85% of your Social Security taxable.
Retirees also frequently overlook state income tax conformity rules. Some states do not conform to federal standard deductions or senior tax relief provisions, producing unexpected state tax liabilities.
Failing to plan for the death of a spouse represents another painful long-term blind spot. Surviving spouses shift from joint brackets to single filer brackets, which cuts tax bracket thresholds in half while living costs remain largely unchanged.
When to Consult a Professional
While basic tax rules are easy to understand, complex retirement scenarios demand professional analysis. A Certified Financial Planner or CPA can model multi-year tax projections tailored to your family goals.
Consider hiring a licensed professional in these specific situations:
- Multi-Year Roth Conversion Modeling: If you hold significant balances in traditional IRAs, an advisor can calculate annual conversion ceilings that prevent IRMAA surcharges and deduction phase-outs.
- Managing Substantial RMD Inflows: When mandatory distributions threaten to push you into punitive tax brackets, a tax professional can integrate QCDs and timing strategies.
- Selling Appreciated Real Estate or Businesses: Transitioning out of major property holdings requires installment modeling or 1031 exchanges to avoid massive single-year capital gains hits.
- Estate and Trust Structuring: Families approaching federal or state estate tax thresholds require sophisticated trust planning to transfer wealth efficiently to future generations.
Working with an expert prevents blind spots and ensures you comply with updated IRS regulations. A well-designed professional plan pays for itself through preserved retirement capital.
Frequently Asked Questions
When do the 2027 IRS tax brackets take effect?
The 2027 tax brackets take effect on January 1, 2027, and apply to all income earned throughout that calendar year. You will use these rates when filing your federal tax return in the spring of 2028.
How much income can a retired couple earn in 2027 without paying federal tax?
A married couple with both spouses age 65 or older can shield up to $48,600 of income in 2027. This amount combines the $33,200 base deduction, two $1,700 age-based additions, and two $6,000 temporary senior deductions.
Does the 3.6% Social Security COLA increase my federal taxes?
Yes, your COLA increase can push your combined income past the frozen $25,000 single or $32,000 joint thresholds. Once past these levels, up to 85% of your Social Security benefit becomes subject to federal income tax.
How does the new Saver’s Match work in 2027?
The Saver’s Match replaces the old Saver’s Credit, providing a direct 50% government match up to $1,000 deposited into your retirement account. The match phases out for single earners above $20,500 and married joint filers above $41,000.
Taking Action on the 2027 Tax Adjustments
The 2027 tax bracket revisions provide welcome breathing room against inflation, but maximizing these adjustments requires deliberate action. Review your anticipated income streams now, including pensions, Social Security, and required distributions, to project your 2027 bracket exposure.
Coordinate withdrawals across taxable, tax-deferred, and tax-free accounts to preserve deductions and keep Medicare premiums predictable. By managing your taxable income around these official thresholds, you protect your savings and secure a worry-free financial future.
This is educational content based on general retirement and financial principles. Individual results vary based on your situation. Always verify current benefit rules, tax laws, and eligibility requirements with official sources like SSA, Medicare.gov, or the IRS.
Last updated: November 2026. Retirement benefits, tax rules, and healthcare regulations change frequently—verify current details with official sources.
Leave a Reply