
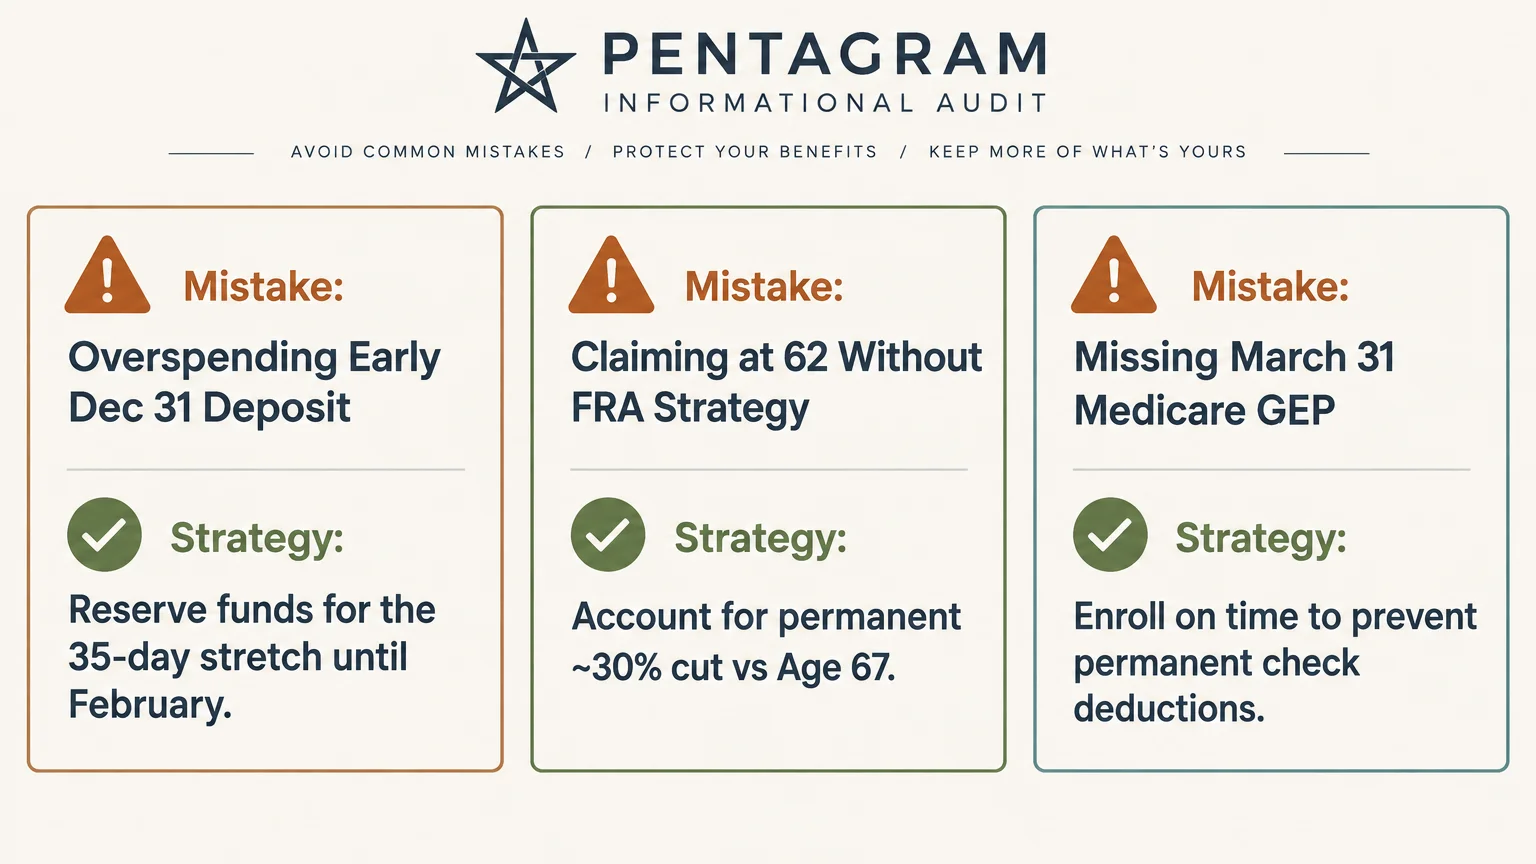
Common Mistakes to Avoid With Your 2027 Benefits
Managing Social Security effectively requires proactive planning rather than passive observation. Avoid these four common missteps that undermine retirement budgets every year.
- Mistaking Early Deposits for Free Bonus Checks. When calendar shifts deliver two checks in April, July, or December, beneficiaries frequently overspend. Remember that an early check simply covers your expenses for the upcoming month.
- Ignoring the Taxable Base Cap on Earnings. High-earning workers often fail to account for the payroll tax cap rising to $192,300. Anticipate continued payroll deductions deeper into the year before realizing take-home pay bumps.
- Failing to Withhold Taxes on Benefits. Receiving gross Social Security checks can produce painful surprises on April 15. Submitting Form W-4V creates automatic tax withholding and eliminates sudden tax season penalties.
- Claiming Early Without Modeling FRA Reductions. With Full Retirement Age now set at 67 for everyone born in 1960 or later, filing early locks in steep permanent reductions. Ensure your savings cannot bridge the gap before locking in lower lifetime checks.
Frequently Asked Questions About 2027 Benefit Dates
Why does my Social Security check arrive on a different day than my spouse’s check?
The Social Security Administration issues retirement payments based on the worker’s day of birth. If you and your spouse were born on different dates across the month, your checks process on different Wednesdays.
Spouses receiving payments based on the primary earner’s record receive deposits according to the primary earner’s birthday. If both partners claim benefits under their own individual work records, each follows their own separate birth date cycle.
What should I do if my scheduled 2027 deposit does not arrive?
First, verify the 2027 calendar for weekend or holiday shifts that may have moved your payment forward. Next, contact your banking institution to verify whether pending electronic transfers exist on your account.
The Social Security Administration requests that you wait three business days past your scheduled deposit date before calling customer support. If your funds remain missing after that window, call the national helpline at 1-800-772-1213.
How does the 3.6% COLA get applied to my Medicare Part B deduction?
The SSA automatically calculates your gross 3.6% COLA increase before deducting your mandatory monthly Medicare Part B premium. The remaining balance represents the net direct deposit transferred into your checking account.
Under federal statutory “hold harmless” protections, your net Social Security check generally cannot decrease year-over-year due to standard Part B premium hikes. Your final December notice confirms your exact net deposit.
Does my Full Retirement Age change if I was born in 1960 or later?
No, age 67 represents the permanent statutory maximum Full Retirement Age under current federal law. Anyone born in 1960 or subsequent years reaches full retirement status at exactly 67 years of age.
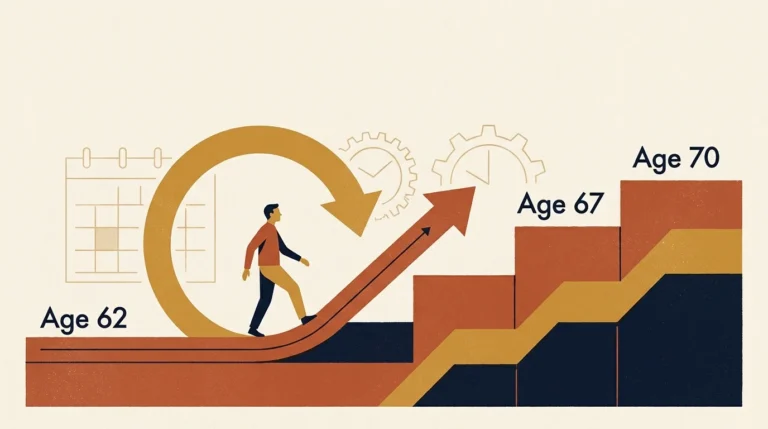
You may still elect to claim reduced retirement benefits as early as age 62 or delay your claim until age 70. Delaying past age 67 earns delayed retirement credits that boost your monthly checks by 8% per year.
Next Steps for Your 2027 Social Security Strategy
Take charge of your retirement finances today by transferring these key payment shifts and deadlines to your wall calendar or smartphone. Tracking dates ahead of time prevents budget stress and protects your monthly purchasing power.
Log into your personal account at SSA.gov to verify that your contact details, direct deposit information, and earnings records remain fully accurate. Staying organized ensures you enjoy the retirement security you spent decades building.
This article provides general retirement education and information only. Every retiree’s situation is unique—what works for others may not work for you. For personalized advice, consider consulting a qualified financial professional such as a CFP or CPA.
Last updated: March 2026. Retirement benefits, tax rules, and healthcare regulations change frequently—verify current details with official sources.
It is a DENIAL for benefit aid as everything goes up EXCEPT amount to qualify for extra help. Rent UP, Food UP, Clothing UP, Healthcare UP-DISCONTINUED OR DROPPED, In 2027, many healthcare providers won’t be in network costing people who need specific coverage to PAY making them poorer or sicker due to no real healthcare coverages. That BIG BEAUTIFUL BILL is a POWDER KEG of stoppages for citizens care from Cancer to Dialysis to prosthetics to needful surgeries for children.