
Master 2027 Social Security Payment Schedule
Understanding the standard Wednesday rotation simplifies your monthly cash management. Beneficiaries receiving payments based on work records established after April 1997 follow this predictable birth-date calendar.
Unlike 2026, no second, third, or fourth Wednesday in 2027 falls on a federal holiday. Juneteenth falls on Saturday, June 19, and Veterans Day lands on Thursday, November 11.
| Month | Birthdays 1st–10th (2nd Wednesday) | Birthdays 11th–20th (3rd Wednesday) | Birthdays 21st–31st (4th Wednesday) | Pre-May 1997 / Dual Eligible (3rd of Month) | SSI Beneficiaries (1st of Month) |
|---|---|---|---|---|---|
| January 2027 | January 13 | January 20 | January 27 | Dec 31, 2026* | Dec 31, 2026* |
| February 2027 | February 10 | February 17 | February 24 | February 3 | February 1 |
| March 2027 | March 10 | March 17 | March 24 | March 3 | March 1 |
| April 2027 | April 14 | April 21 | April 28 | April 2* | April 1 |
| May 2027 | May 12 | May 19 | May 26 | May 3 | April 30* |
| June 2027 | June 9 | June 16 | June 23 | June 3 | June 1 |
| July 2027 | July 14 | July 21 | July 28 | July 2* | July 1 |
| August 2027 | August 11 | August 18 | August 25 | August 3 | July 30* |
| September 2027 | September 8 | September 15 | September 22 | September 3 | September 1 |
| October 2027 | October 13 | October 20 | October 27 | October 1* | October 1 |
| November 2027 | November 10 | November 17 | November 24 | November 3 | November 1 |
| December 2027 | December 8 | December 15 | December 22 | December 3 | December 1 |
*Denotes an early disbursement caused by a weekend or observed federal banking holiday. Source: SSA Publication No. 05-10031.
Working While Receiving Benefits: Navigating the 2027 Earnings Test
If you collect Social Security before reaching full retirement age and continue to work, federal earnings limits apply directly to your compensation. Exceeding these statutory thresholds leads to withheld benefits.
For beneficiaries who remain under Full Retirement Age throughout all of 2027, the annual earnings limit rises to $25,560. The agency withholds $1 in benefits for every $2 earned above that cap.
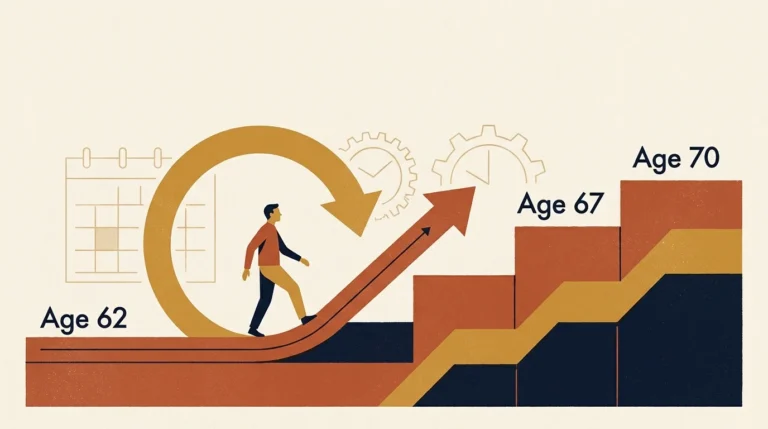
A separate, more generous rule applies during the calendar year you reach Full Retirement Age. In 2027, this applies to individuals born in 1960 reaching age 67.
For those reaching age 67 during 2027, the earnings threshold jumps to $67,920. The SSA withholds $1 for every $3 earned above this limit, counting only earnings generated before the month you turn 67.
The month you reach your full retirement age of 67, the earnings cap vanishes entirely. You can earn unlimited wages from employment without losing a single dollar of your monthly Social Security benefit.
Remember that withheld benefits are not permanently forfeited. When you attain full retirement age, the agency recalculates your monthly benefit upward to credit you for the checks withheld during working years.
Professional vs. Self-Guided: Managing Your Benefit Timeline
Deciding whether to handle benefit management on your own or hire a financial professional depends on your family structure, health, and income complexity. Consider these practical scenarios to select the right approach.
- Scenario 1: Single Filer with Fixed Income. If Social Security represents your primary income source alongside small savings, self-guiding through the official online portal works well. Tracking payment dates on your calendar provides sufficient control.
- Scenario 2: The Working Early Claimer. If you claim benefits at 62 while earning substantial wages, consult a CPA or financial planner. Professional modeling ensures you avoid surprise withholding penalties and unexpected tax bills.
- Scenario 3: Married Couples with Divergent Earnings. Navigating spousal benefits, survivor benefits, and optimal claiming ages requires strategic analysis. A fee-only financial planner can calculate how staggered claiming dates maximize lifetime household wealth.
- Scenario 4: High Net Worth Retiree Facing Taxation. If you draw income from pensions, traditional IRAs, and taxable investments, partner with a tax specialist. They will structure withdrawals to keep provisional income beneath punitive Social Security taxation thresholds.
It is a DENIAL for benefit aid as everything goes up EXCEPT amount to qualify for extra help. Rent UP, Food UP, Clothing UP, Healthcare UP-DISCONTINUED OR DROPPED, In 2027, many healthcare providers won’t be in network costing people who need specific coverage to PAY making them poorer or sicker due to no real healthcare coverages. That BIG BEAUTIFUL BILL is a POWDER KEG of stoppages for citizens care from Cancer to Dialysis to prosthetics to needful surgeries for children.