Retired in America

Your Guide to a Confident Retirement

  • Home
  • Personal finance
  • Retirement Life
  • Saving & Spending

6 Easy Steps to Estimate Your Social Security Benefits

June 10, 2026 · Retirement Life
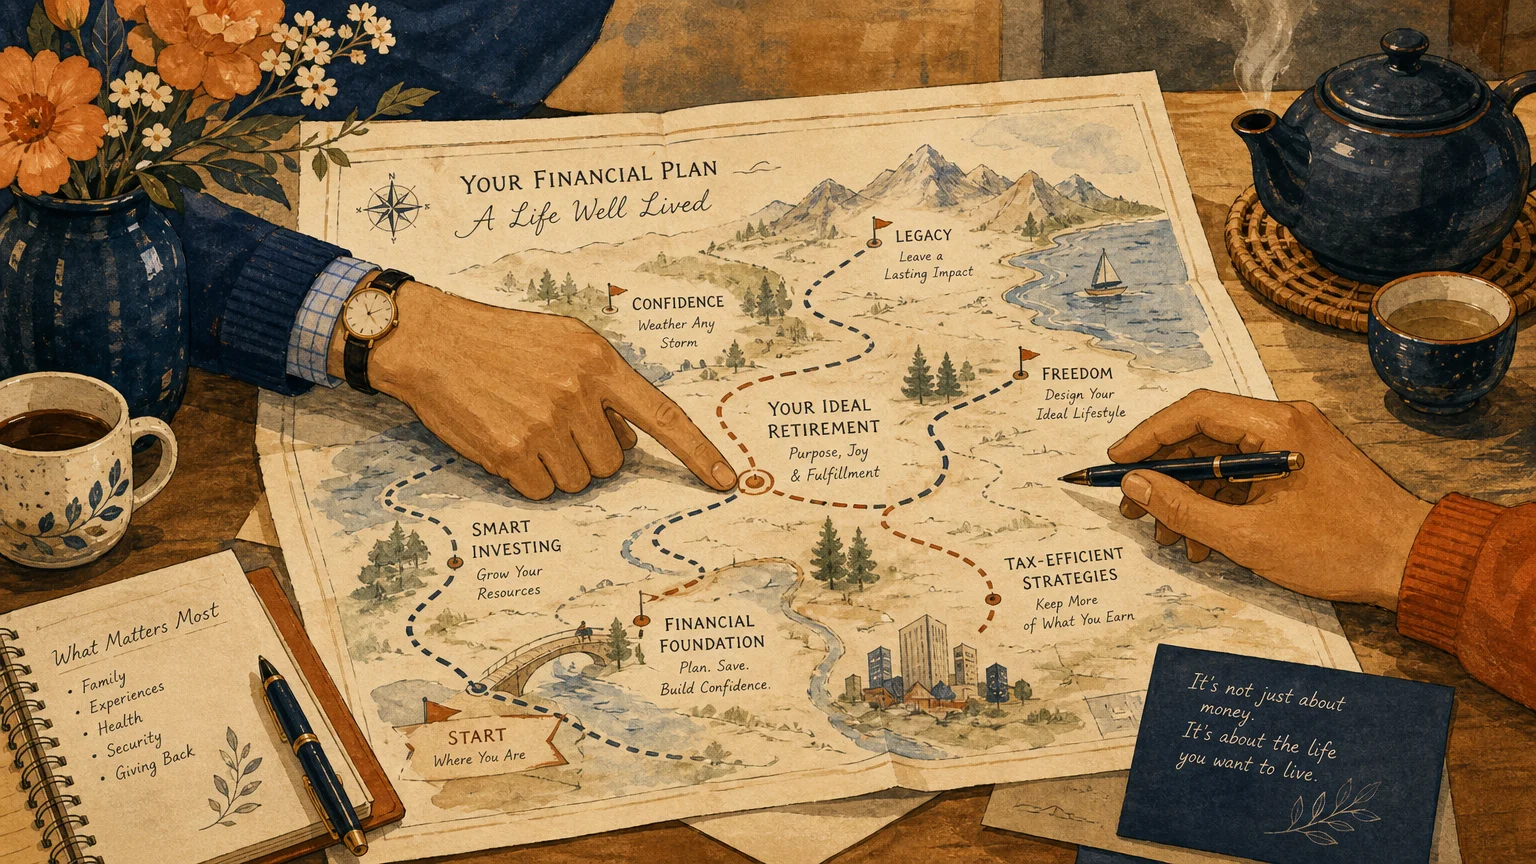
A warm gouache illustration showing two people's hands reviewing a financial plan over a cup of tea.
Two hands examine a detailed financial map, illustrating why professional guidance is essential for complex retirement goals.

When DIY Isn’t Enough

For many Americans, estimating benefits using the online portal provides all the clarity needed. However, certain financial backgrounds introduce layers of complexity that automated calculators struggle to process. If your situation falls into one of the following categories, consider consulting a fiduciary professional from the Certified Financial Planner Board.

You Have a Non-Covered Pension: If you spent part of your career working for a state government, a local municipality, or a school district that did not withhold Social Security taxes, you may be subject to the Windfall Elimination Provision (WEP) or the Government Pension Offset (GPO). These rules drastically reduce your Social Security benefits to account for the pension you receive from non-covered employment. Standard calculators routinely fail to account for WEP and GPO, resulting in wildly inflated estimates.

Complex Business Ownership: Small business owners often manipulate their salary and owner distributions to minimize self-employment taxes. While legally sound for tax purposes, this strategy artificially depresses your reported lifetime earnings, resulting in a much lower Social Security benefit. A financial planner can help you model the long-term tradeoff between paying fewer taxes today versus receiving smaller guaranteed checks in retirement.

Multiple Marriages and Divorces: If you have been married and divorced multiple times, and each marriage lasted at least 10 years, you have options. You can choose to claim against the highest-earning ex-spouse’s record. Navigating the paperwork and identifying which record yields the highest survivor or spousal benefit often requires professional analysis to ensure you don’t leave thousands of dollars on the table.

Frequently Asked Questions

Does my Social Security estimate include future cost-of-living adjustments (COLAs)?

No, your standard online estimate shows your benefit in today’s dollars without projecting future inflation. The SSA applies Cost-of-Living Adjustments (COLAs) annually based on the Consumer Price Index. Because inflation is unpredictable, the SSA uses current-year purchasing power to give you a realistic baseline for what your benefit will buy.

Can I get an estimate if I don’t have enough credits yet?

You need 40 credits (roughly 10 years of work) to qualify for retirement benefits. If you have fewer than 40 credits, your online account will inform you that you are not currently eligible. However, it will track your progress, showing exactly how many more credits you need to earn before a benefit estimate can be generated.

How does part-time work in retirement affect my estimated benefit?

If you have already reached your Full Retirement Age, part-time work does not negatively impact your benefits—you can earn as much as you want. If you are under FRA, earning above the annual threshold triggers the earnings test, which temporarily withholds a portion of your monthly check. On the positive side, if your part-time income replaces one of your lower-earning years in your 35-year history, the SSA will automatically recalculate and permanently increase your benefit.

Will my estimated benefit decrease if the Social Security trust fund runs out?

The Social Security system operates largely on a pay-as-you-go basis, funded by current payroll taxes. Even if the reserve trust funds were fully depleted, incoming tax revenue would still cover the vast majority of promised benefits (historically estimated around 75% to 80%). Congress has numerous legislative options—such as adjusting the FRA, increasing the payroll tax rate, or changing the taxable maximum—to prevent a reduction in benefits before trust fund depletion occurs.

Estimating your Social Security benefits empowers you to take control of your retirement timeline. Start by logging into your online account today to verify your earnings record and review your baseline numbers. Once you have your data, run scenarios for different claiming ages and factor in the reality of taxes and Medicare premiums. By replacing guesswork with concrete mathematics, you build a resilient financial plan capable of supporting the retirement lifestyle you have worked decades to achieve.

This is educational content based on general retirement and financial principles. Individual results vary based on your situation. Always verify current benefit rules, tax laws, and eligibility requirements with official sources like SSA, Medicare.gov, or the IRS.


Last updated: June 2026. Retirement benefits, tax rules, and healthcare regulations change frequently—verify current details with official sources.
Pages: 1 2 3 4 5 6 7 8

Share this article

Facebook Twitter Pinterest LinkedIn Email

4 responses to “6 Easy Steps to Estimate Your Social Security Benefits”

  1. Jimmie Williams says:
    July 6, 2026 at 5:50 pm

    I have read this email and i honestly don’t understand what am supposed to do at this time

    Reply
  2. Jeff says:
    July 10, 2026 at 12:36 am

    Start at Step 1: Set up an account.

    Reply
  3. Terry says:
    September 3, 2026 at 8:32 am

    They don’t want you to understand. That’s more money left in the system

    Reply
  4. Terry says:
    September 3, 2026 at 8:33 am

    Control control control

    Reply

Leave a Reply Cancel reply

Your email address will not be published. Required fields are marked *

Search

Latest Posts

  • Social Security Administration letters dropping through a brass door mail slot into a green collection basket. 8 Social Security Letters to Watch for This Winter
  • A mature couple smiling and riding cruiser bicycles along a wooden boardwalk beside tropical coastal waters and sailboats. 12 Retirement Destinations That Feel Like a Vacation
  • A senior man sits on a park bench sketching in a notebook along a brick path lined with historic southern homes. 12 Retirement Towns With Low Taxes and Mild Winters
  • Illustration of a Social Security check alongside deduction blocks labeled FICA, Medicare, Medicaid, and Taxes. 7 Things That Could Shrink Your Social Security Check in 2027
  • A senior man in an armchair reads a Social Security Administration letter in a sunlit home library with a sleeping cat. Turning 73 in 2027? Your Social Security Taxes Could Jump
  • Smiling woman with gray hair wearing an apron and browsing a book in a sunlit plant and bookstore. Social Security's 2027 Earnings Limit Rises to $25,560 for Working Retirees Under 67
  • A middle-aged man and woman review a household expense planner at a workbench in an open garage. What Social Security Cuts Could Cost a Middle-Class Couple Every Year
  • A woman sitting at a dining table reviews printed paperwork alongside a laptop, calculator, and notebook. The IRS Has Released 2027 Tax Brackets - Here's What They Mean for You
  • Smiling older couple shopping together inside a sunlit greenhouse filled with potted plants and ceramic pots. Spousal Social Security Benefits See the Biggest Raise in 4 Years – What Couples Should Know
  • A man standing outdoors by a roadside mailbox holding a white envelope on a rainy autumn day. $500 Obamacare Refunds Are Headed to Nearly 1 Million Americans – Do You Qualify?

Newsletter

Get retirement planning tips, savings strategies, and lifestyle insights delivered to your inbox.

Related Articles

9 Costs You Should Consider When Drafting Your Retirement Budget

Entertainment Retirement comes with a lot of free time and opportunities to discover new hobbies,…

Read More →
An older woman looks over healthcare paperwork at her kitchen table under warm light, looking concerned.

7 Signs Your Medicare Advantage Plan Restricts Specialist Access

Discover the 7 signs your Medicare Advantage plan restricts specialist access, including narrow networks, prior…

Read More →

Will Taxing the Rich Save Social Security? Experts Weigh in

Grand columns frame the Department of Justice, the institution overseeing the legalities of federal payroll…

Read More →

5 Signs You’re Emotionally Ready for Retirement

How will I fill my time? – We rarely comprehend the amount of free time we…

Read More →

Thinking of Retiring Early? These Real-Life Tips Can Help You Do Just That

A woman explores her passion for painting in a bright studio filled with plants and…

Read More →
Senior couple walking arm in arm along a brick sidewalk past a bakery, bookstore, and cafe table with coffee.

11 Signs You’ve Chosen the Right Retirement Town

Discover eleven undeniable signs that you have selected the right retirement town for your personal…

Read More →

10 Forgotten Restaurants Americans Miss The Most

8. Kenny Rogers Roasters: A Healthier Fast Food Dream Country music superstar Kenny Rogers teamed…

Read More →

10 Most Important Retirement Age Milestones You Need to Consider

Age 66 Those born between 1943 and 1954 are eligible to receive their full Social…

Read More →
An illustration of an older couple looking out over a historic European town from a quiet cafe balcony.

4 Most Overrated (and Overpriced) Travel Destinations for Seniors – And Where to Go Instead

Discover why famous spots like Paris and Venice are overrated for older adults, and explore…

Read More →
Retired in America

Your Guide to a Confident Retirement

Inedit Agency S.R.L.
Bucharest, Romania

contact@retiredinamerica.com

Trust & Legal

About Us

Editorial Policy

Advertiser Disclosure

Frequently Asked Questions

Contact Us

Disclaimer

Terms and Conditions

Privacy Policy

Subscribe

Unsubscribe

Categories

  • Personal finance
  • Retirement Life
  • Saving & Spending

© 2026 Retired in America. All rights reserved.