The Impact on Early Retirees Facing the 2026 Subsidy Cliff
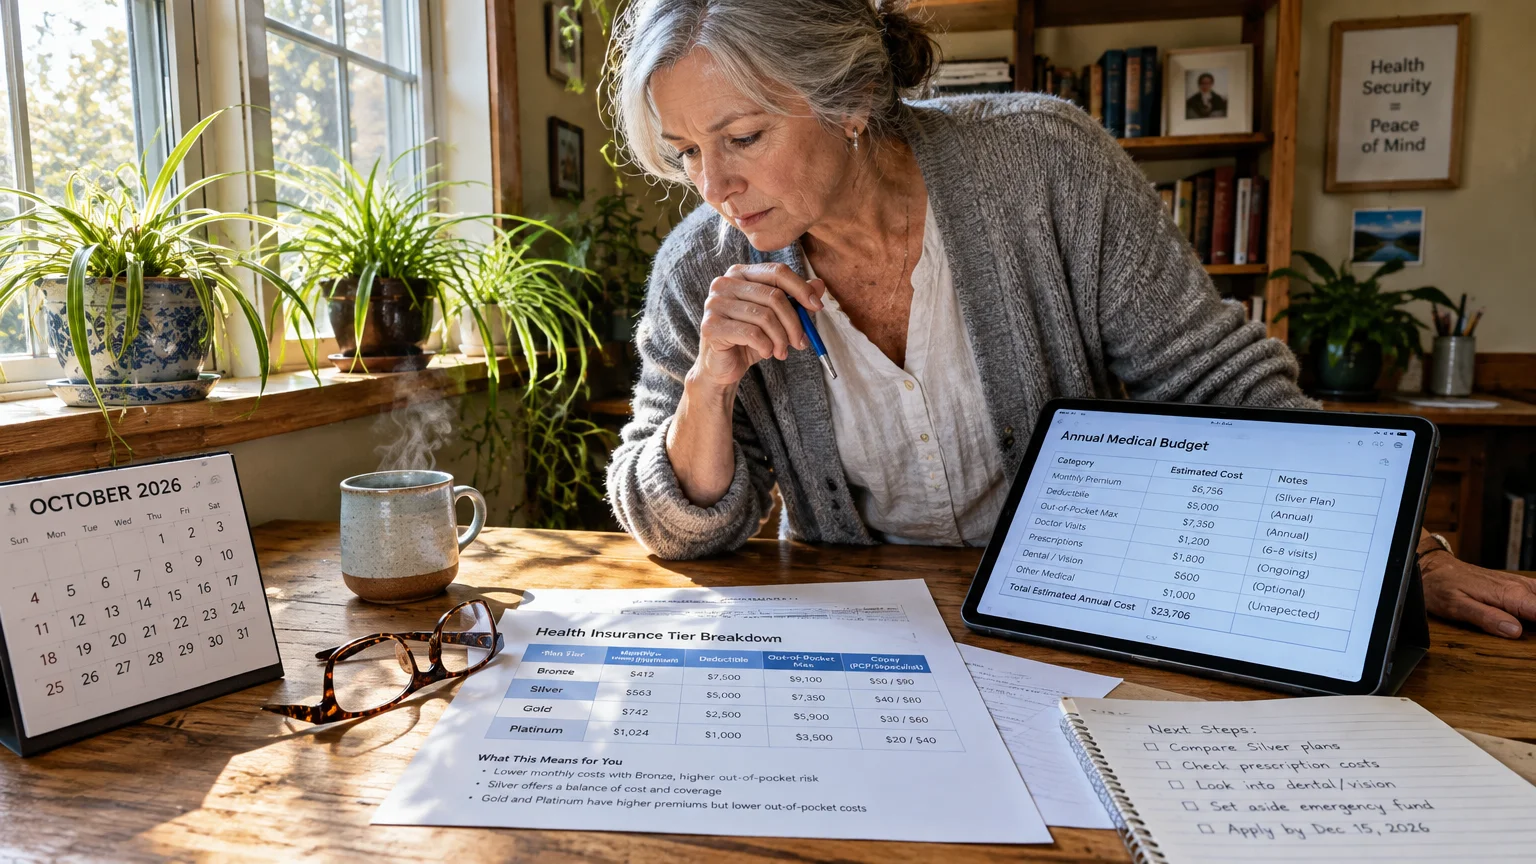
Adults retiring before age 65 face unique hurdles bridging coverage until Medicare begins. Pandemic-era subsidies that capped benchmark premiums at 8.5% of income expired at the end of 2025.
Their expiration reinstated the 2026 “subsidy cliff.” Exceeding 400% of the poverty level by one dollar eliminates all assistance, leaving you responsible for full sticker prices.
KFF reports unsubsidized HealthCare.gov premiums rose by an average of $2,184 between 2025 and 2026. Because insurers can charge 60-year-olds three times more than 21-year-olds, older adults bear the heaviest burden.
For example, a 60-year-old earning $65,000 (roughly 415% FPL) saw annual premiums jump by over $10,300, reaching nearly $16,000 per year.
In this context, a one-time $500 obamacare refund offers modest relief, offsetting only a small fraction of that $10,300 annual increase.
Comparing ACA Relief Options: User Fee Refunds vs. MLR Rebates
Policyholders often confuse this user fee rebate with mandatory Medical Loss Ratio (MLR) rebates. Federal law requires insurers to spend 80% to 85% of premiums on clinical care or refund the difference.
While MLR rebates stem from insurer profits, this working families refund originates from surplus government exchange fees. The table below details the core differences.
| Feature | Working Families Refund | Medical Loss Ratio (MLR) Rebate | Premium Tax Credit (Subsidy) |
|---|---|---|---|
| Source of Funds | Surplus HealthCare.gov user fees | Excess insurer administrative margins | Federal tax revenue |
| Payment Frequency | One-time payout (Fall 2026) | Annual (if insurer misses targets) | Monthly discount or annual tax credit |
| Standard Amount | Flat $500 per person | Varies widely by carrier performance | Sliding scale based on household income |
| Income Limits | Strictly for incomes over 400% FPL | No income limitations | Must fall below 400% FPL (in 2026) |
| State Limitations | Restricted to 30 HealthCare.gov states | Applies nationwide in all 50 states | Applies nationwide in all 50 states |
| Distribution Method | U.S. Treasury check or direct deposit | Insurer premium credit or paper check | Direct reduction in monthly billing |
You could qualify for an MLR rebate from your insurer while remaining ineligible for the federal user fee payout.

Leave a Reply